Written by Kadek Darma
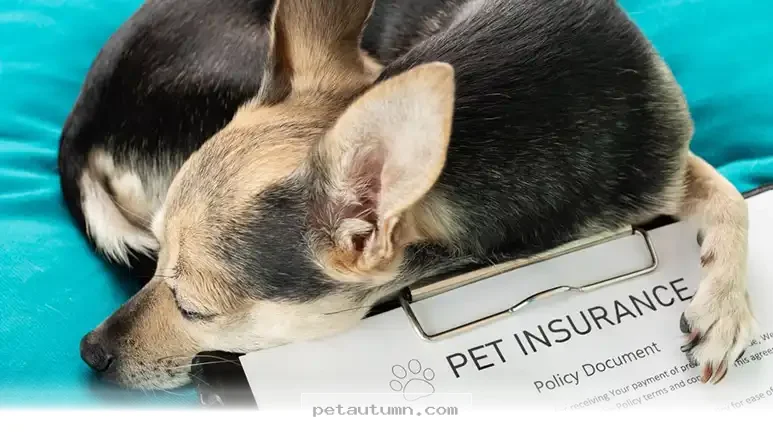
Managing your dog’s healthcare expenses can feel like a daunting task, especially when you consider how quickly emergency vet bills add up. With the rising costs of modern veterinary care, many pet parents find themselves wondering if an insurance policy is a wise financial move or just another monthly bill.
It is helpful to view pet insurance through the lens of risk management rather than a simple savings plan. Taking the time to weigh the long-term costs against the potential for unexpected medical emergencies will help you make the best decision for your pup and your bank account.
Key Takeaways
- Pet insurance is a form of risk management; compare plans carefully to avoid surprise exclusions.
- Monthly premiums typically increase as your dog ages, which can impact your long-term budget.
- Always read the fine print regarding pre-existing conditions and breed-specific health limitations.
- Consider alternatives like a dedicated high-yield savings account if you prefer full control over your funds.
- Insurance is most effective for unexpected accidents and illnesses rather than routine wellness visits.
Is Pet Insurance Right for Your Dog?
The pet insurance market has expanded rapidly, with many companies now even offering coverage as a voluntary employee benefit. While the convenience of a payroll deduction might sound appealing, it does not replace the necessity of conducting your own thorough research.
Before signing a contract, you should treat the process with the same level of scrutiny you would apply to your own health or auto insurance. Marketing messages often lean heavily on emotional appeals, but your focus must remain on the actual policy language and coverage limits.
1. Common Pitfalls to Avoid
Many pet owners experience sticker shock when they discover that a specific procedure or chronic condition is excluded from their policy. You might assume your dog is covered for everything, but insurance providers often define coverage narrowly based on specific diagnostic codes.
Always look for clear definitions of what constitutes a "pre-existing condition" within your policy documents. If your dog has a history of skin allergies or joint issues, these may be excluded entirely from future coverage, leaving you responsible for the full cost of treatment.
2. Evaluating the Financial Reality
To determine if a policy is worth the cost, you should compare the total premiums paid over several years against the average cost of major veterinary procedures in your area. If you are diligent about setting aside money, self-insuring can sometimes be more cost-effective.
| Feature | Pet Insurance | Emergency Fund (Self-Insure) |
|---|---|---|
| Monthly Cost | Fixed Premium | Flexible Contributions |
| Coverage | Varies by Plan | Total Control |
| Pre-existing Conditions | Usually Excluded | N/A |
| Out-of-Pocket | Deductibles & Co-pays | Total Bill |
Color key: Green = Positive, Yellow = Caution, Red = Warning.
3. Pros and Cons of Coverage
Choosing the right path requires an honest look at your financial habits and your dog’s specific health needs. Every dog owner has different priorities, so evaluate these common factors before you commit to a long-term contract.
Pros of Pet Insurance
- Provides a predictable monthly expense for budgeting purposes.
- Can offer significant financial relief during catastrophic accidents or major surgeries.
- Allows you to make medical decisions based on treatment rather than immediate affordability.
Cons of Pet Insurance
- Premiums often rise significantly as your dog reaches their senior years.
- Most plans do not cover routine care, vaccinations, or dental cleanings.
- You are still required to pay the vet upfront and wait for reimbursement.
4. Alternatives to Traditional Insurance
If you decide that a traditional policy is not the right fit, you have other ways to prepare for potential veterinary costs. Building a dedicated "pet health" savings account is a popular strategy for owners who want to avoid paying premiums for coverage they might never use.
- Emergency Savings: Automate monthly transfers into a high-interest savings account specifically for your dog.
- Veterinary Discount Plans: Some clinics offer wellness packages that bundle annual exams and vaccines for a flat fee.
- Credit Options: Keep a low-interest credit line available strictly for unexpected medical emergencies.
5. Essential Questions for Providers
When you narrow down your choices, do not be afraid to contact the insurance companies directly with specific questions. Getting clear answers in writing can prevent a massive headache if you ever need to file a claim.
- How exactly does this company define a pre-existing condition for a senior dog?
- Will my monthly premiums increase based on my dog’s age or claim history?
- Does the plan include a lifetime limit on payouts for chronic illnesses?
- What is the specific process for submitting a claim, and how long is the typical turnaround?
The information on petautumn.com is for general informational purposes only and does not constitute veterinary advice. Pet health needs vary by breed, age, and individual condition. Always consult a licensed veterinarian before making decisions about your pet’s health, diet, or medical treatment. Pet Autumn is not affiliated with any veterinary organization, pet food manufacturer, or breeder.
Ultimately, the goal is to ensure your dog has access to the care they need throughout their life. Whether you choose to carry an insurance policy or build a robust emergency fund, the most important step is having a plan in place before an emergency arises.
Take a moment to review your dog’s medical history and your current financial situation to decide which path offers you the most peace of mind. By preparing today, you can focus on enjoying your time together rather than worrying about the unexpected costs of pet ownership.
Dog care writer at petautumn.com. Visual Communication Design graduate (S.Ds) from Universitas Udayana. Covers dog breeds, behavior, training, and gear reviews. Dog dad to Meepo. Based in Austin, Texas.